Transaction Center
Time to bring it home. Find zipForm®, transaction tools, and all the closing resources you'll need. Except for the champagne — that's on you.
View the latest sales and price numbers. Find out where sales will be in upcoming months.
Get a roundup of weekly economic and market news that matters to real estate and your business.
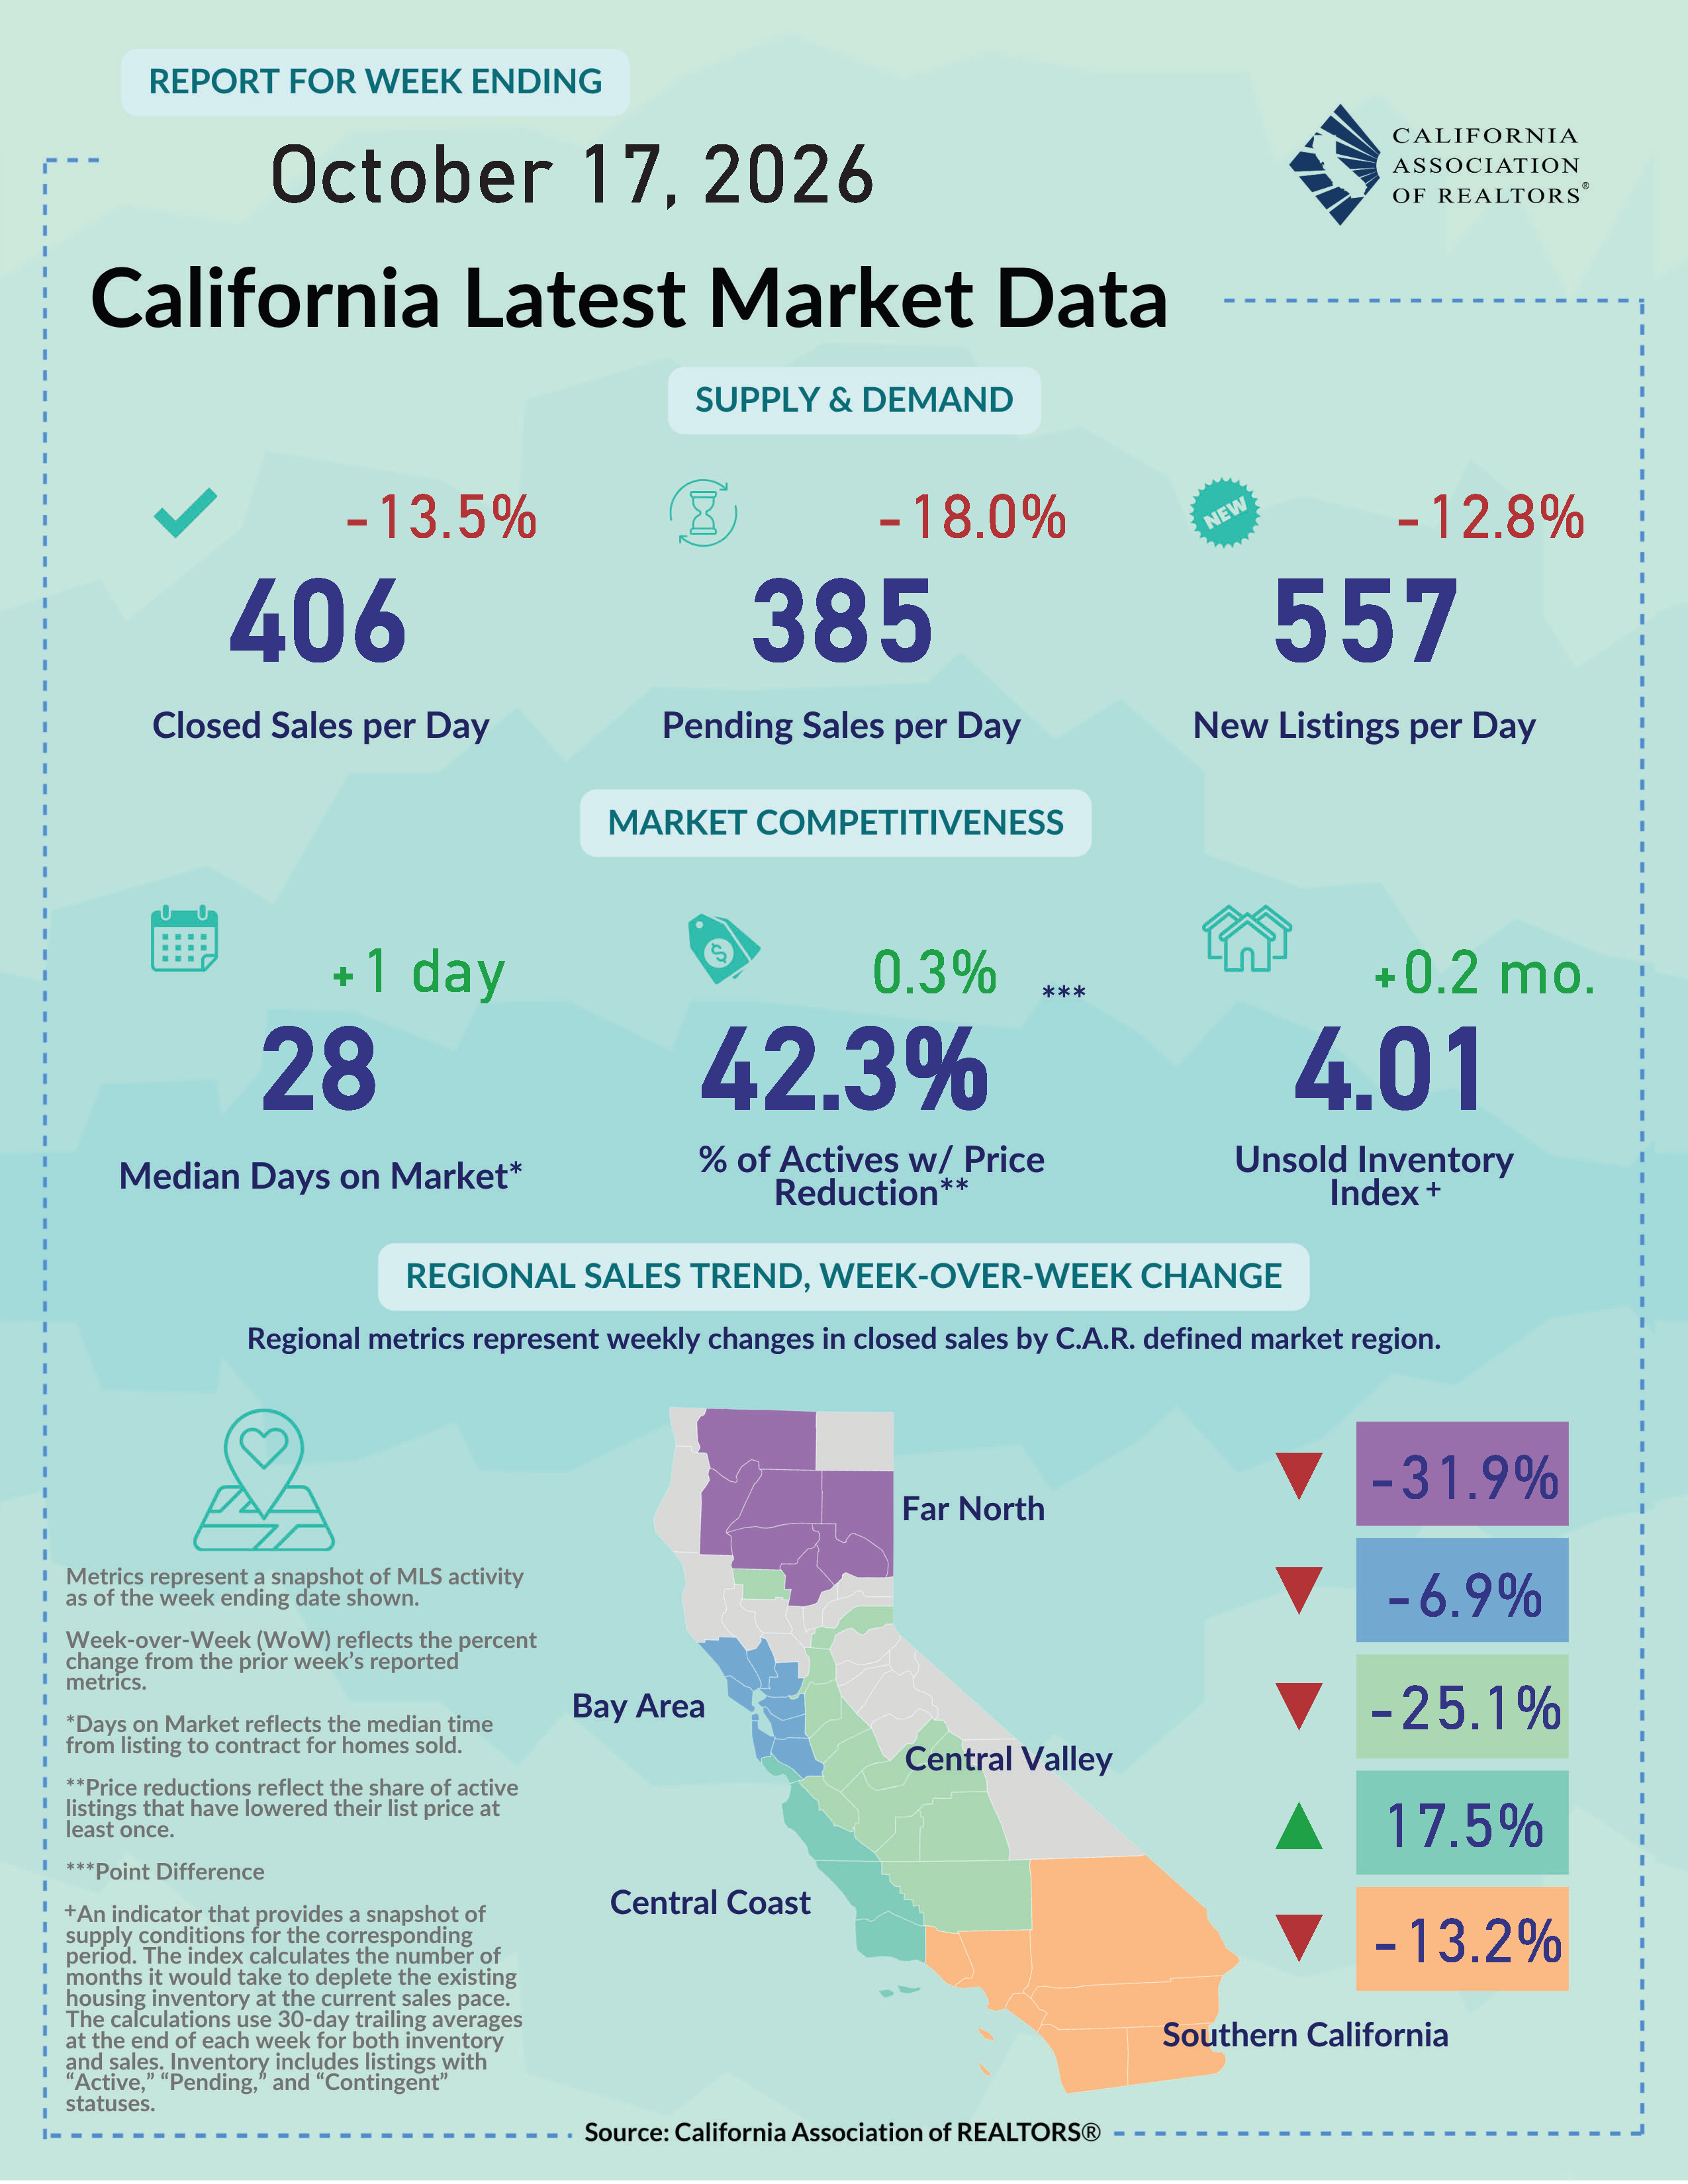
Gain insights through interactive dashboards and downloadable infographic reports.
All Shareable Reports All Interactive DashboardsCatch up with the latest outreaches and webinars by the Research and Economics team.
C.A.R. conducts research with members and consumers on a regular basis to get a better understanding of the housing market and the real estate industry.
California Model MLS Rules, Issues Briefing Papers, and other articles and materials related to MLS policy.
Looking for information on how to file an interboard arbitration complaint? You've come to the right place! Find the rules, timeline and filing documents here.
Summaries and photos of California REALTORS® who violated the Code of Ethics and were disciplined with a fine, letter of reprimand, suspension, or expulsion.
The most recent edition of the Code of Ethics and Standards of Practice of the National Association of REALTORS® along with other important links to NAR information.
The California Professional Standards Reference Manual, Local Association Forms, NAR materials and other materials related to Code of Ethics enforcement and arbitration.
Designed to expand housing access, Proposition 37 proposes a $25 billion state bond program providing eligible middle-income homebuyers with fixed-rate second mortgages covering up to 17% toward the purchase of newly constructed homes.
Updates on C.A.R.'s legislative advocacy efforts in Sacramento.
Ballot MeasuresIssues briefing papers, handbooks and other background materials on local policy issues that affect real estate.
CREPAC, LCRC, IMPAC, ALF and the RAF comprise C.A.R.'s political fundraising arm.
The RAA: Protecting REALTORS® and Homeownership REALTOR® Action FundC.A.R. Senior Vice President of Government Affairs Sanjay Wagle sits down with California Insurance Commissioner Ricardo Lara to discuss the current state of California’s insurance market,
Learn how you can make a difference, by getting involved yourself or by passing along valuable information to your clients.


|
October 19, 2026 - The effects of the recent surge in mortgage rates are beginning to surface more clearly in California’s housing market, while elevated energy costs and persistent inflation continue to weigh on the broader economy. Home sales have weakened and small businesses remain cautious, even as consumer spending holds up and home prices remain relatively stable. Uncertainty could persist over the coming months, keeping housing activity subdued and borrowing costs elevated. An easing of geopolitical tensions, however, could help moderate inflation pressures and pave the way for gradually improving economic conditions and a more favorable lending environment in early 2027. Statewide home sales hit an eight-month low: California home sales fell below their year-ago level for the first time in six months and recorded their sharpest drop in nearly three years. Existing single-family home sales declined 3.4% from August to a seasonally adjusted annualized rate of 260,410 units, down 6.5% from the revised 278,540-unit pace recorded in September 2025 and reached the lowest level since January. The decline from last year was the largest dip since October 2023, and statewide sales remained below the 300,000-unit benchmark for the 48th consecutive month. For the first nine months of the year, existing single-family home sales were up 0.8% on a year-to-date basis. Pending sales also weakened further last month, with a decline of 12.1% from the prior month and 15.8% dip from a year ago. The annual loss, in fact, was the largest year-over-year decrease in pending sales since August 2023. With mortgage rates rising sharply since late August, persistent affordability challenges will likely weigh on homebuying activity for the rest of the year. Home prices remain relatively stable: The median sold price for California’s existing single-family homes remained relatively stable in September, with a dip of only 0.2% from August to $899,720. The mild decline was smaller than the 1.8% average decrease typically observed between August and September over the past 10 years. On a year-over-year basis, the median price increased 1.7%, marking the fifth consecutive month of annual gains. Despite a pullback in demand due to economic uncertainty and higher mortgage rates, a bigger share of high-priced properties to total homes sold had an effect on the statewide median price and kept its monthly decline relatively stable last month. The share of million-dollar home sales increased to 35.9% in September from 35.2% in August, reversing three consecutive months of declines. With lower-priced home purchases typically more sensitive to rate increases, mix of sales changes could continue to play a bigger-than-usual role in median-price movement in the coming months. Consumer prices outpace consensus expectations: High energy prices pushed up inflation more than expected, with the September headline consumer price index rising 0.6% month-over-month and 3.7% year-over-year. The annual increase recorded last month came in higher than the 3.6% expected by economists and was the largest jump in the past four months. Gas prices were the primary driver of the surge last month, with fuel oil jumping 74.2% from a year ago and gasoline soaring 34.2% from its year-ago level. Core inflation, which strips out volatile food and energy prices, also surpassed the consensus expectation with a 0.2% monthly gain and a 2.6% yearly increase. Shelter costs, in particular, rose 0.4% from August and the increase was the fastest monthly rate in five months. The energy shock from the Middle East conflict is keeping inflation high, eroding workers’ wage gains, and creating more affordability challenges for Americans. The latest data on inflation may have put more pressure on the central bank and increased the odds of a rate hike in the upcoming October FOMC meeting. Consumers continue to spend in September: U.S. retail sales expanded with their growth pace exceeding consensus expectations, and the jump was partly due to rising gasoline prices, according to the latest report released by the Commerce Department. September sales at retail and food services increased 0.8% from August after surging 1.3% in the prior month and recorded a 6.3% year-over-year gain over September 2025. The increase in retail sales was due partly to higher gas prices, as spending at gas stations shot up by 28.1% from 12 months ago. Total sales excluding sales at gasoline stations increased more moderately by 4.5% on a year-over-year basis. While discretionary goods and services remained solid in the latest report, traditional grocery and essentials staple sectors continued to stall with annual growth registering less than 1% in September. Overall, consumer spending appears resilient but future spending could be curtailed if gas prices remain elevated. Small business optimism dips again as business conditions remain uncertain: Businesses continue to be wary about the future despite consumer spending growing at a healthy pace. The NFIB’s Small Business Optimism Index declined for the second straight month by 0.8 points to 97.9 from August and dipped below its 52-year average of 98.0 for the first time in three months. Rising costs, surging interest rates, and the difficulty in finding qualified workers are all negatively impacting the business environment, while the mid-term elections and the Middle East conflict continue to create uncertainty. Fewer small business owners anticipated the outlook for the general business environment to improve in the short term, as a net 6% expected better conditions in the next six months, a drop of 4 points from August. Inflation metrics also worsened last month, with the net percent of owners raising average selling prices remaining steady at 31%, while the net percent who plan to increase prices in the next three months climbing 3 points from August to 31%. With energy prices remaining elevated and the Federal Reserve likely to raise rates again before the end of the year, business optimism may not improve much over the next couple of months. Note: This summary report gets updated every Monday by 6:00 pm PST. Feel free to email us at [email protected] if you have any questions and/or feedback.
|
|